Saturday, January 5, 2019

A walkthrough on the factors that affect health insurance premium

Image result for age affect health insurance premium
Image source: theinsurance24x7.blogspot.com

Health insurance is the most necessary protection plan when one decides to buy an insurance protection for oneself and family members. To save oneself from financial trouble emerging from health issues or emergency in the future, it’s important to purchase a best-rated health insurance plan.

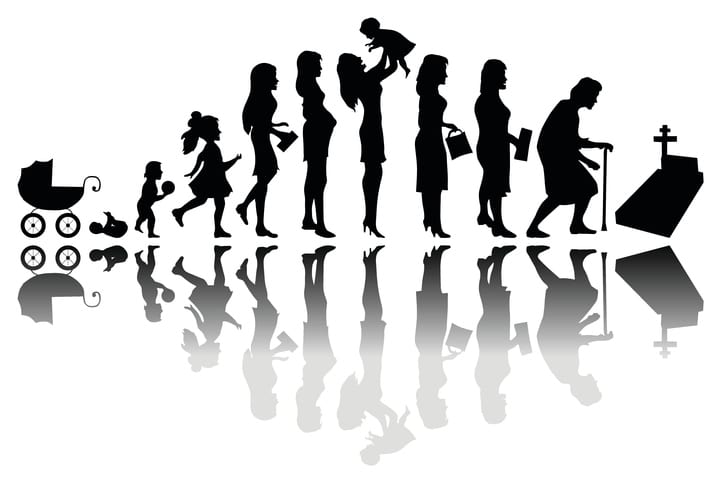
Before buying a health insurance plan, one must always compare the cost and benefits offered by different insurers. Playing a critical role in the purchasing process of family health insurance, premium amounts are affected by a number of factors. One’s premium amount is less if purchased at a young age. It is the most decisive factor that has an impact on the cost of a premium. Location also affects one’s premium rate; people who live in metropolitan cities are more prone to health issues, with medical costs being more expensive in such areas.

Family size matters, and the family floater sum assured is extended to one family including spouse and children. While the cost incurred in purchasing a family floater does not break the bank, a family of four will have to pay a higher premium amount compared to a family of two.
Image result for work affect health insurance premium
Image source: commonwealthfund.org
Gender plays a role in health insurance premiums, and women are charged more by insurers, as they believe that women use more pharmaceuticals, see the doctor more often, and are more vulnerable to chronic illnesses. In addition, pregnancy is factored in the premium. Family medical history may be used as justification for higher health insurance premiums. The nature of one’s work also plays a role in affecting premium amounts, especially for jobs involving high injury rates, hazardous chemicals, international business travel, and others.

Delos H. Yancey III is the president and CEO of State Mutual Insurance, a legal reserve mutual insurer headquartered in Rome, Georgia. For more information about the company and its work, head over to this website.

Friday, January 4, 2019

How to maximize MediGap insurance

Image result for maximize MediGap insurance
Image source: pbs.org

Also known as MediGap, Medicare supplement insurance helps take the costs not included in the coverage provided by original Medicare. Taken together, the two policies can help pay for a broad assortment of medical bills and reduce the amount of out-of-pocket medical expenditures. For many older adults, MediGap insurance is an excellent investment, providing the coverage necessary to prevent surprise hospitalization expenses.

Medicare supplement insurance coverage, however, can vary broadly. It is also important to remember that MediGap insurance cannot cover long-term care costs, nor can it pay for dental care, vision care, and, in many cases, prescription drugs. Moreover, MediGap coverage is individual; for your spouse to be covered, you would need to buy one.

Image result for maximize MediGap insurance
Image source: pbs.org
Many companies offer a basic package of MediGap insurance policies that come in lettered plans. Despite differences in other individual offerings, which vary by the company, each type of lettered plan has a mandated set of fixed benefits that are uniform throughout multiple states, with few exceptions. MediGap providers in Massachusetts, Minnesota, or Wisconsin are subject to different governing laws.

Some standard plans (E, H, I, and J) can no longer be purchased by new subscribers, and the previous standard plan of choice in the past few years, Plan F, is being discontinued in 2019. In the past, many people have preferred MediGap Plan F because of its comprehensive coverage; Plan G is a recommended alternative that offers similar coverage.

For individuals under original Medicare, the best times to acquire MediGap insurance are within at least a day after one’s 65th birthday or up to six months of signing up for Medicare Plan B. This would allow them to guarantee their coverage and purchase it at the best price available.

Delos H. Yancey is the CEO of State Mutual insurance, which provides coverage for policyholders across 44 states and the District of Columbia. Visit his company’s website for more on its policies.

Wednesday, December 12, 2018

Key moments when you should update your life insurance policy

Life events usually occur around the start or end of a cycle (iStock)
Image source: thedailynet.com
A lot of people tend to forget to update their insurance policies. It’s easy to regard life insurance as just one of your monthly bills. Changes in premiums happen all the time, and it’s not often that these are explained to us. However, certain life changes mean you have to revisit your insurance policy. Here are some key moments in life that should trigger a call to your insurance agent.

You are getting married or getting a divorce: If you are gaining or losing a dependent, you need to update your insurance policy. Not doing so could either not include them into your plan or you’ll be paying a higher premium for a person you are no longer with.

You have children: If you’re not planning on getting a separate insurance plan for your children, you may want to include them in yours. Increasing your coverage is just one of the many options that is readily available to you. Such changes can help secure your children’s financial future, help them later on with education expenses, or simply see to it that they are honored part of your estate if the unthinkable occurs.
Image result for update your life insurance policy
Image source: nationwide.com
You got a new job: Depending on which way your salary went, you need to revisit your insurance policies. It could be possible to be burdened with an insurance premium that’s too expensive for your new job. At the same time, upgrading your coverage is a good choice if you got a significant pay increase.

You finally retired: For people who are part of a group life insurance policy through an employer, retiring would mean losing the coverage. Now that you’re relying on insurance as your income adjusting it according to your lifestyle is necessary.

Delos H. Yancey III is the chairman, president, and CEO of State Mutual Insurance. He is a Certified Financial Examiner, a Certified Insurance Examiner, and a fellow of the LIMRA Leadership Institute. Visit his company's website for more on its services and history.

Monday, December 3, 2018

Top mistakes for first-time life insurance buyers

Image result for Top mistakes for first-time life insurance buyers
Image source: money.usnews.com

Getting life insurance is a major milestone for any adult. It gives you peace of mind and is a great way to invest on your future retirement. However, given the importance of getting insurance, there are still people who make mistakes when enrolling for a plan for the first time. These mistakes could mean paying a higher premium for unwanted or unnecessary coverage. Here are some of the top mistakes first-time life insurance buyers make.

One of the biggest mistakes one could make is buying life insurance offered to them by family members or friends. You may trust them with your life and their intentions may be good, but getting the same insurance as people close to you or offered by family and friends without knowing all the terms might not give you what you need later on.

Another major mistake is getting swept away by the terms without actually thinking if the coverage fits your situation. The best insurance plans take into consideration a person’s needs, wants, and a budget they are comfortable with. Not being able to pay monthly premiums could ruin this long-term commitment.

Image result for Top mistakes for first-time life insurance buyers
Image source: kiplinger.com
Making all beneficiaries primary beneficiaries is also a common mistake. This can have major consequences as primary beneficiaries receive both benefits of your insurance policy and the burden of paying debts. If primary beneficiaries are not appointed properly, your insurance benefits could be divided unevenly and cause trouble for those you will leave behind.

Lastly, failing to update insurance plans occurs often. When new health-related issues arise, your insurance may not cover it. When these situations occur, refer back to your plan or your insurance provider.

Delos H. Yancey III is the chairman, president, and CEO of State Mutual Insurance. He is a Certified Financial Examiner, a Certified Insurance Examiner, and a fellow of the LIMRA Leadership Institute. Visit his company's website for more on information regarding services and its history.

Thursday, November 8, 2018

Top mistakes for first-time life insurance buyers

Image result for mistakes for first-time life insurance buyers
Image source: forbes.com

Getting life insurance is a major milestone for any adult. It gives you peace of mind and is a great way to invest on your future retirement. However, given the importance of getting insurance, there are still people who make mistakes when enrolling for a plan for the first time. These mistakes could mean paying a higher premium for unwanted or unnecessary coverage. Here are some of the top mistakes first-time life insurance buyers make.

One of the biggest mistakes one could make is buying life insurance offered to them by family members or friends. You may trust them with your life and their intentions may be good, but getting the same insurance as people close to you or offered by family and friends without knowing all the terms might not give you what you need later on.

Image source: planetrating.com

Another major mistake is getting swept away by the terms without actually thinking if the coverage fits your situation. The best insurance plans take into consideration a person’s needs, wants, and a budget they are comfortable with. Not being able to pay monthly premiums could ruin this long-term commitment.

Making all beneficiaries primary beneficiaries is also a common mistake. This can have major consequences as primary beneficiaries receive both benefits of your insurance policy and the burden of paying debts. If primary beneficiaries are not appointed properly, your insurance benefits could be divided unevenly and cause trouble for those you will leave behind.

Lastly, failing to update insurance plans occurs often. When new health-related issues arise, your insurance may not cover it. When these situations occur, refer back to your plan or your insurance provider.

Delos H. Yancey III is the chairman, president, and CEO of State Mutual Insurance. He is a Certified Financial Examiner, a Certified Insurance Examiner, and a fellow of the LIMRA Leadership Institute. Visit his company's website for more on information regarding services and its history.

Friday, October 19, 2018

The differences between mutual and stock insurance


Related image
Image source: monolitestate.com

Most insurance companies can be classified into one of these two categories: mutual and stock. Some exceptions to these are fraternal organizations that offer the same service; examples are Blue Cross or Blue Shield. Across the world, mutual insurance companies are more common. However, in the U.S., there are more stock insurers than mutual ones.

The policies the two types of insurers do not differ that much. Their main difference lies in the form of ownership. In a stock insurance company, the owners are the shareholders, or stockholders if the organization is a publicly traded corporation.

On the other hand, a mutual insurance company is owned by the policyholders, who are also referred to as “contractual creditors.” They are afforded voting rights in the selection of the board of directors and management.

Image result for stock and mutual insurance
Image source: eandlinsurance.com
Because of the difference in ownership forms, the two types of insurers also contrast in the distribution of earned income and profits from investments. Stock insurers have an objective making a profit for their shareholders, doling out dividends when the company has a positive cash flow.

For mutual insurers, the goal is to meet the financial expectations and serve the needs of the policyholders, who are generally more interested in long-term financial gains than short-term financial demands.

Delos Yancey is a Certified Financial Examiner, a Certified Insurance Examiner, and a fellow of the LIMRA Leadership Institute. He is also the chairman of State Mutual Insurance, a mutual insurance company that is run for the benefit of its policyholders. Check out this blog to learn more about the insurance industry.

Thursday, September 27, 2018

Common insurance policies you should seriously consider getting

Image result for insurance policies
Image source: solarrenovate.com

When looking for the most apt insurance policy for your needs and financial planning goals, it’s important to study the options carefully. Policies come with various features and add-ons, and the price will depend on the number of benefits included. The idea is to safeguard your most important assets.

Topping the list of must-have insurance policies is life insurance. This is important in ensuring that your dependents maintain financial stability when you’ve moved on. Study your annual income and decide on a plan that effectively replaces your earnings. Among other things, a life insurance covers burial costs and mortgage expenses, which can prove to be a huge burden for those you’ll leave behind.

Related image
Image source: trasferirsiinspagnaconfamiglia.it
 A solid homeowner's insurance plan will make the process of replacing your home easier to deal with. Choose one that covers the cost of living somewhere else while your house is being renovated, as well as the needed structural replacement and the house’s amenities. While you’re computing, also keep in mind the cost of possible upgrades you might want to have.

It’s also great to be ready for possible future disability. Getting a long-term disability insurance will compensate for your compromised earning power if you can no longer work. This often comes hand in hand with a sound health insurance policy that will get you more financially ready for the rising costs of medical care should you fall ill. Just consider the argument that having one is much better than having to regret later as you deal with medical expenses.

Delos H. Yancey is the chairman, president, and CEO of State Mutual Insurance. He is a Certified Financial and Insurance Examiner and a fellow of the LIMRA Leadership Institute. Click this link for more information on Mr. Yancey and his company.